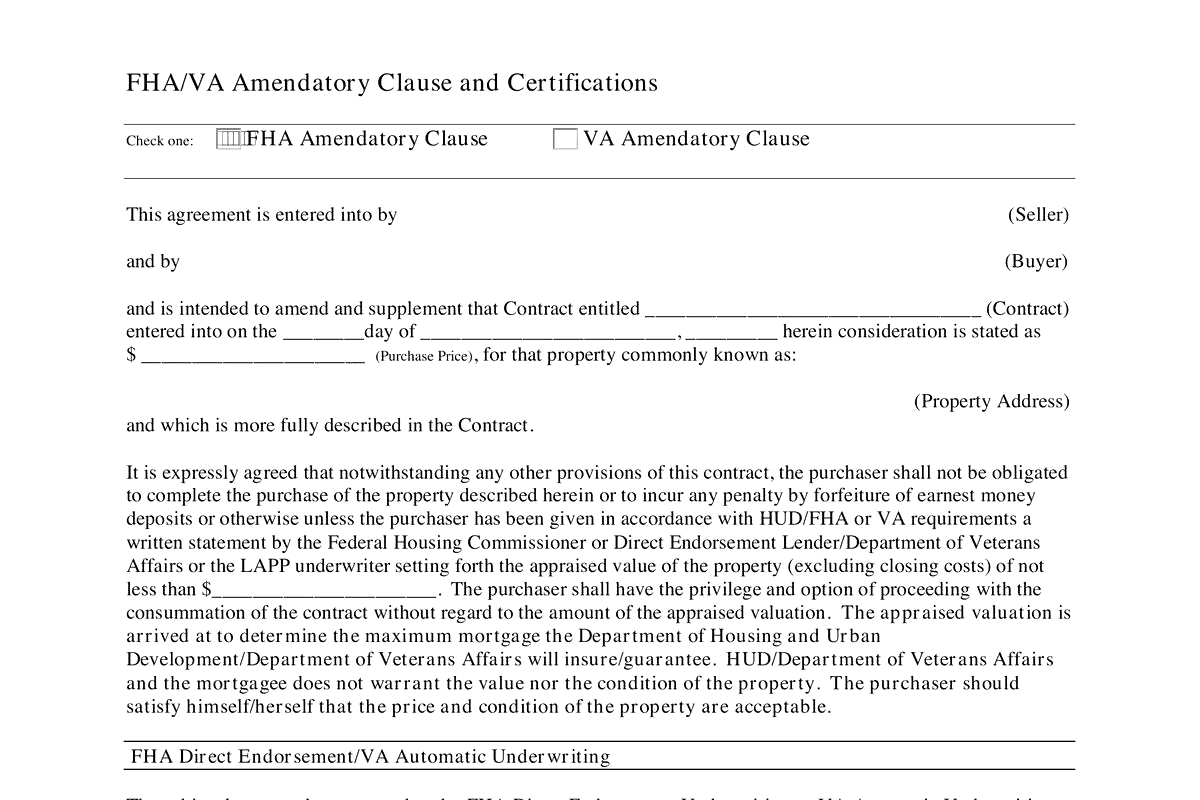
A Lender Document With a Twin in the TREC Form
On every FHA or VA file, a one-page document called the amendatory clause shows up from the lender, and someone asks whether the seller really has to sign it. They do. And the protection it describes is already in the Texas contract.
Here’s what it says, where it lives in the TREC forms, and what it means when the appraisal comes in under the price.
Table of Contents
▼What the Amendatory Clause Says
The clause is required by HUD on FHA-insured loans and by VA on VA-guaranteed loans. In Texas, the same language is built into Paragraph 4 of the TREC Third Party Financing Addendum (40-11), the “FHA/VA Required Provision.” From the current form:
"…the purchaser (Buyer) shall not be obligated to complete the purchase of the Property described herein or to incur any penalty by forfeiture of earnest money deposits or otherwise: (i) unless the Buyer has been given in accordance with HUD/FHA or VA requirements a written statement issued by the Federal Housing Commissioner, Department of Veterans Affairs, or a Direct Endorsement Lender setting forth the appraised value of the Property of not less than $____ or (ii) if the contract purchase price or cost exceeds the reasonable value of the Property established by the Department of Veterans Affairs."
In plain English: if the FHA or VA value comes in below the number in that blank, the buyer doesn’t have to close and doesn’t lose the earnest money.
The blank is usually the sales price. Check that it’s filled in.
The Rest of Paragraph 4
4A: The buyer can still close. The buyer has “the privilege and option of proceeding with consummation of the contract without regard to the amount of the appraised valuation” or the VA’s reasonable value.
4B: FHA’s value is about the loan, not the house. On FHA, the appraised value determines the maximum mortgage HUD will insure. HUD doesn’t warrant the value or condition of the property, and the buyer should be satisfied with both.
4C: VA’s cash rule and the seller’s option. If a VA buyer chooses to pay more than the VA’s reasonable value, the excess is paid in cash from a source the buyer discloses to VA, and it can’t be borrowed funds except as VA approves. And if the reasonable value is below the sales price, the seller may reduce the price to the reasonable value and the sale closes at the lower price, with proportionate adjustments to the down payment and loan amount.
No 3-day deadline. Paragraph 4 says the 3-day notice of termination requirement in Paragraph 2B doesn’t apply to Paragraph 4. That’s different from Property Approval on a conventional loan.
Why the Lender Sends a Separate Copy
If it’s already in the TREC form, why sign it again? Because the lender has to document the clause for HUD or VA on its own paperwork, regardless of what the state contract says. In our experience, every FHA and VA lender sends its own version for the buyer and seller to sign. It’s normal, and it doesn’t change the deal.
The practical point for the file: it needs signatures from both sides, often early in the loan process, and a missing seller signature can hold up the loan. Treat it like any other lender condition.
How It Compares to the Appraisal Addendum
On a conventional loan, the buyer can waive or partially waive the appraisal termination right with the appraisal addendum (TREC 49-1). That form says it’s not for FHA or VA financing.
On FHA and VA, there’s no waiver box. The protection is always in the deal. The buyer can choose to close anyway (Paragraph 4A), but can’t promise in advance to give up the right the way a conventional buyer can with 49-1.
That’s one reason some listing agents see FHA and VA offers as carrying more appraisal risk. The other is that the appraisal can follow the property: an FHA appraisal is generally tied to the property for 180 days and a VA Notice of Value for six months. The lender can confirm what applies on a given file.
When the FHA or VA Appraisal Comes In Low
Same options as any low appraisal, with a few VA specifics:
- The seller reduces the price. On VA, Paragraph 4C spells this out: reduce to the reasonable value and close at the lower price.
- The buyer pays the difference in cash. On VA, from a disclosed source, not borrowed funds except as VA approves.
- They meet in the middle.
- The buyer doesn’t proceed under Paragraph 4, and the earnest money is refunded.
On VA files, the Tidewater process can give the agents a short window to send comps before the appraisal is finalized, if the appraiser expects the value to fall short. Speed matters there. See VA loan transactions in Texas.
Any price change goes on a written amendment signed by both parties. Whether a buyer properly exercised the Paragraph 4 right on a particular file is a legal question for a real estate attorney.
What the Clause Does and Doesn’t Cover
It doesn’t add a new right. The lender’s amendatory clause restates the protection already in Paragraph 4 of the financing addendum. Both parties usually sign the lender’s copy.
Closing anyway costs cash. If the value comes in low and the buyer chooses to close at the contract price, the difference comes out of the buyer’s cash.
It’s about value, not repairs. Repairs the FHA or VA appraiser calls out are a separate issue under Paragraph 7E of the resale contract. See lender-required repairs.
How Our TCs Handle It
The amendatory clause comes from the lender, so we don’t fill it out. What we do:
- Confirm the FHA or VA box on the Third Party Financing Addendum and that the Paragraph 4 value blank is filled in, and flag anything missing to you
- Introduce ourselves to the lender, title and the co-broke agent, and follow the appraisal or Notice of Value in our weekly updates
- If the clause sets a deadline, it goes on the deadline timeline and we remind you before it
- Let you know the day the value comes in
- If the price changes, fill out the amendment only at your specific written direction, track signatures and deliver it to title and the lender, and update the deadline timeline
You’re copied on everything, and the Thursday status report shows where the loan stands.