The Two-Page Form Nobody Reads Until the Appraisal Lands
Most agents attach the appraisal addendum and forget it. Then the appraisal comes back under the contract price and the whole file turns on which box got checked.
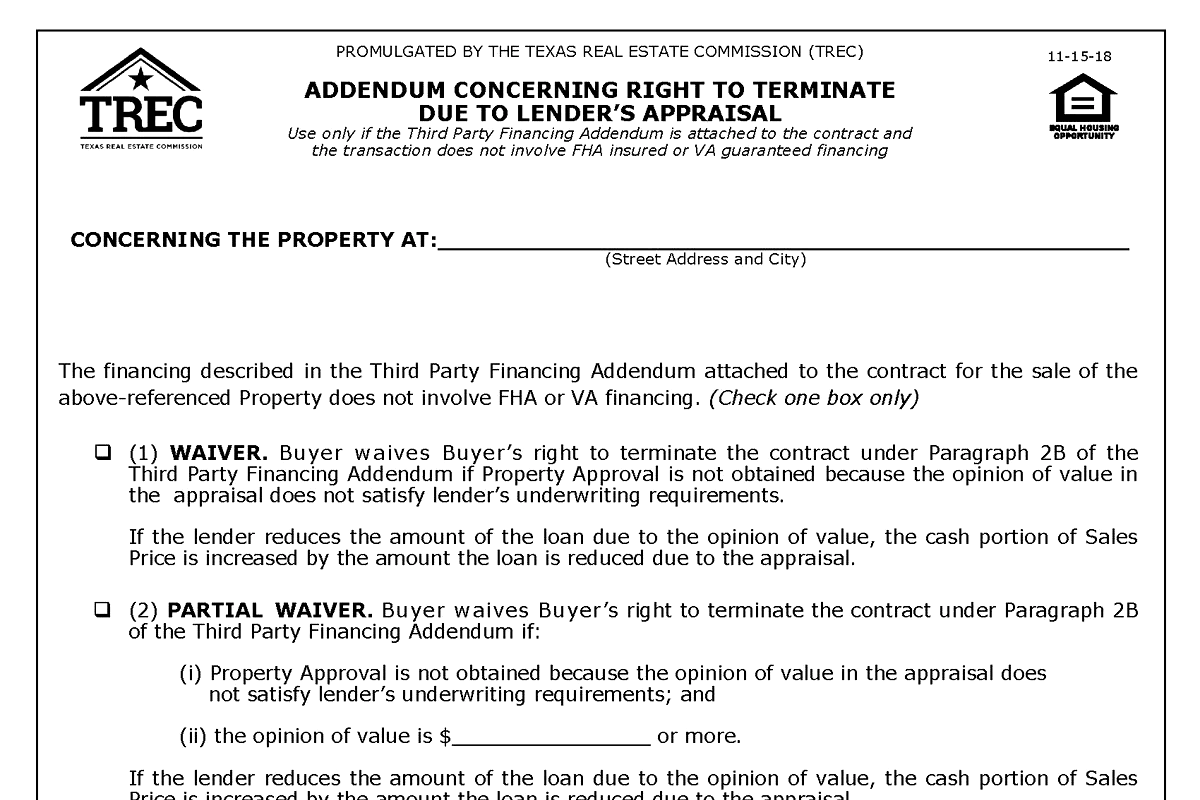
The form is TREC 49-1, the Addendum Concerning Right to Terminate Due to Lender’s Appraisal. This guide covers what each box does, how it works with the Third Party Financing Addendum, and what happens when the number comes in low.
Table of Contents
▼What TREC 49-1 Is
TREC 49-1 has been in use since 2019 and is still the current version on trec.texas.gov. The header on the form sets its limits: “Use only if the Third Party Financing Addendum is attached to the contract and the transaction does not involve FHA insured or VA guaranteed financing.”
So it’s for conventional and other non-government financing. No cash deals. No FHA or VA, which have their own appraisal protection in Paragraph 4 of the financing addendum (see the FHA/VA amendatory clause).
You’ll also hear it called “the appraisal addendum,” “the appraisal waiver” or, from out-of-state agents, “the appraisal contingency.” In Texas they all mean this form.
Where the Appraisal Right Comes From in the First Place
This is the part that gets missed. The buyer’s right to walk over the appraisal doesn’t start with 49-1. It starts with the Third Party Financing Addendum.
Paragraph 2B of that addendum (Property Approval) says that if the buyer’s lender determines the property doesn’t satisfy its underwriting requirements, “including but not limited to appraisal, insurability, and lender required repairs,” the buyer may terminate on or before the 3rd day before the Closing Date, with a copy of the lender’s written statement of reasons. The earnest money is refunded.
TREC 49-1 modifies that Paragraph 2B right for the appraisal piece only. It doesn’t touch insurability or lender-required repairs.
The Three Boxes
The form says to check one box only.
Box 1: Waiver
The buyer waives the right to terminate under Paragraph 2B if Property Approval isn’t obtained because the opinion of value doesn’t satisfy the lender’s underwriting requirements.
Then the line that matters: “If the lender reduces the amount of the loan due to the opinion of value, the cash portion of Sales Price is increased by the amount the loan is reduced due to the appraisal.”
In plain English, the buyer brings more cash. The sales price doesn’t change.
Box 2: Partial Waiver
Same waiver, but only if the opinion of value is at or above a dollar amount written into the blank. Below that floor, the buyer keeps the Paragraph 2B appraisal right.
Example: The sales price is $400,000 and the floor is $380,000. The appraisal comes in at $385,000: the buyer has waived the appraisal termination right and covers the gap if the lender cuts the loan. The appraisal comes in at $375,000: the waiver doesn’t apply, and the buyer still has the Paragraph 2B right.
The same cash-portion language from Box 1 applies.
Box 3: Additional Right to Terminate
This one goes the other way. It adds a right on top of Paragraph 2B. The buyer may terminate within a set number of days after the Effective Date if:
- the appraised value, according to the appraisal from the buyer’s lender, is less than a dollar amount written into the form; and
- the buyer delivers a copy of the appraisal to the seller.
If the buyer terminates under Box 3, the earnest money is refunded. This right doesn’t depend on whether the lender would still make the loan. It’s a straight number test with its own deadline.
On the Notice of Buyer’s Termination, Box 3 has its own checkbox, and the appraisal copy has to go with it.
What Happens When the Appraisal Comes In Low
A low appraisal opens a negotiation. What each side can do depends on the boxes.
No 49-1 attached. The Paragraph 2B right is intact. If the lender determines the property doesn’t satisfy its requirements because of the value, the buyer can terminate by the 3rd day before closing with the lender’s written statement. Whether a given lender response meets that test is a contract question. If the parties disagree about it, that’s for a real estate attorney.
Box 1 checked. The buyer can’t terminate under Paragraph 2B because of value. If the lender reduces the loan, the buyer covers the difference in cash.
Box 2 checked. Above the floor, same as Box 1. Below it, the buyer keeps the Paragraph 2B right.
Box 3 checked. If the appraisal is under the stated number and it’s still inside the stated days, the buyer can terminate with a copy of the appraisal, regardless of what the lender decides.
In practice, most low appraisals we see end in one of four ways:
- The seller lowers the price to the appraised value, or part of the way.
- The buyer brings more cash to cover the gap.
- They split it.
- The buyer terminates, if a right to do so still exists.
Any price change goes on a written amendment to the contract, signed by both parties. The lender needs it before it can update the loan. A Reconsideration of Value can be requested through the lender when the appraiser missed relevant sales, but in our experience it rarely moves the number much without strong comps.
Waivers, Box 3 and FHA/VA Appraisals
A waiver is a commitment to cover the gap in cash. Under Box 1, a low appraisal doesn’t give the buyer a way out. If the buyer can’t cover the difference, the earnest money is what’s at risk.
Box 3 has its own deadline. When it’s in the contract, the deadline often falls well before closing, and it goes on the deadline timeline like the option period.
FHA and VA appraisals follow the property. An FHA appraisal is generally tied to the property for 180 days and a VA Notice of Value for six months. If an FHA or VA deal ends over value, the next FHA or VA buyer may face the same number. The lender can confirm the details.
Whether the buyer has a valid termination right on a particular file is a legal question. When the parties disagree, that’s for a real estate attorney.
How Our TCs Handle It
We fill out the TREC 49-1 only at your specific written direction. Which box and what numbers come from you and your client. We don’t recommend a box, negotiate the gap or advise on value.
Then we:
- Send the completed addendum to you to review and take to your client
- Track signatures and confirm it’s attached to the contract with the financing addendum
- Add the Box 3 deadline, if there is one, to the deadline timeline, along with the Property Approval deadline (3 days before closing), with 48-hour reminders to you
- Follow the appraisal with the lender in our weekly updates and let you know the day it’s in
- If the price changes, fill out the amendment only at your specific written direction, track signatures and deliver it to title and the lender
You’re copied on everything, and the Monday key-dates report shows where the appraisal stands.